The flows are back. Gulf crude exports ran near prewar levels, a record number of companies guided profits above estimates, and AI spending keeps climbing. The bills moved instead. Iran resumed hitting tankers, the 10-year yield shrugged off a weak jobs report, and most companies can't predict what their AI will cost. Each cost is landing on whoever has the thinnest cushion. 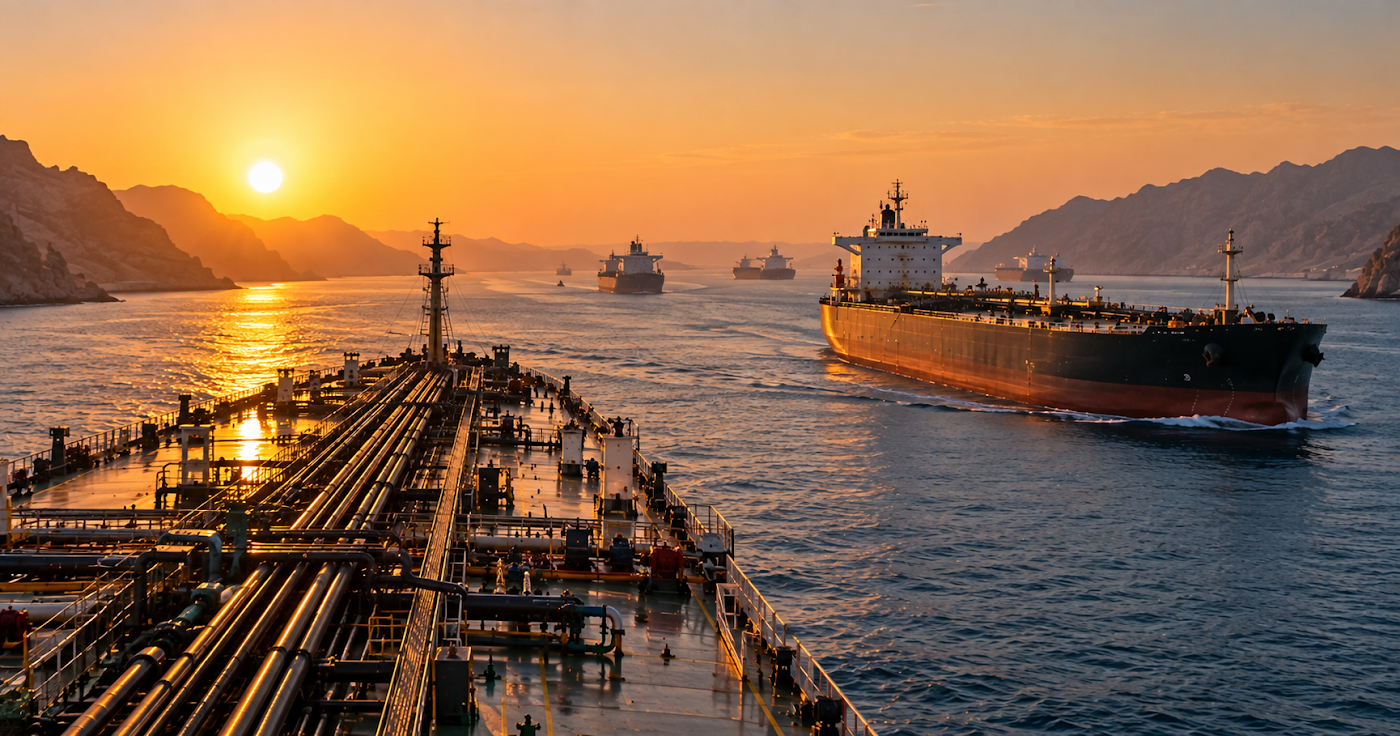
| 01 | Oil Is Moving Again. Someone Is Paying the Toll.Crude got cheaper at the source this weekend. It did not get cheaper to move or store. |
| Riyadh Is Paying Buyers to Brave HormuzGulf exports excluding Iran averaged at least 16.5 million barrels a day in September, near prewar levels, Kpler data show. Then the attacks came back. British maritime monitors have logged seven strikes near the strait since Sept. 28, plus another reported Sunday. Shuttle runs cost $15 to $20 a barrel before insurance. Over the weekend, Saudi Arabia cut its November price for Asia to $5 below the regional benchmark, its widest discount since June 2020, while raising Europe's. The seller is now eating part of the freight. |
| Small Truckers Are Running Out of RoadDiesel averaged $6.37 a gallon Friday, AAA said, 15 cents off its September record. Independent truckers, who buy their own fuel, take the hit. One driver's 151-gallon fill-up in Texas cost $944, against about $500 a year ago. More than a dozen small carriers have filed for bankruptcy in the past month, and few have the leverage big fleets use to win fuel surcharges. G7 leaders agreed Friday to release 100 million barrels, diesel first. Heating-oil futures fell 3.2%. |
| Europe Is Betting the Winter on WeatherEurope's gas storage is 72% full, the lowest on record for early October, against an average of 90% in 2022 to 2025. Qatar has shipped 536 fewer LNG cargoes than a year earlier. Most bet on El Niño. Six One Commodities ran today's storage through the past ten winters, and three would have needed emergency measures. Gas for delivery now costs more than gas for later. The market is paying everyone to wait. |
Outlier Signal Crude has mostly recovered, and its price now reflects the cost of carrying it. Producers pay for shuttles, and Riyadh discounts its oil to keep Asian buyers. Moving barrels make the crisis look like it is fading. The risk has shifted downstream. Fuel and gas stocks are thin, and nobody is paid to hold more, so small truckers and European utilities absorb the next strike or cold snap. If Europe's storage passes 80% by November while heating-oil futures hold Friday's drop, buffers are rebuilding. If tanker data confirm Gulf flows are slowing, the toll becomes the price. | 02 | Profits Are Carrying What Yields Took AwayThe Nasdaq set a record with the 10-year near a 24-year high. Only one kind of asset managed it. |
| Bad News for Jobs Was No Help to Long BondsSeptember's 29,000 jobs knocked the 10-year yield to about 5.16% early Friday. By afternoon it was back at 5.28%, near its highest since 2002, as short rates fell on hopes for a Fed pause. The pressure is spreading. Top-rated corporate bond yields topped 6% last week for the first time since 2023. Troubled commercial property loans hit 12% of conduit bond pools, above the Covid-era peak of 8.5%. Polymarket now gives the 10-year a 64% chance of touching 5.4% before 2027. |
| Record Guidance Is Holding Up a Narrow MarketA record 72 S&P 500 companies issued third-quarter profit forecasts above estimates, FactSet says, topping the 65 set in 2021. Tech supplied 44 of them. Earnings are doing all the lifting. The S&P 500 trades below 19 times forward earnings, down from above 21 in May, yet sits within 1% of its record. The Nasdaq hit a high Friday with only about 21% of S&P 500 stocks above their 50-day averages. Investors are paying less for each dollar of profit and buying more dollars. |
| Bitcoin Showed What Rates Do Without EarningsBitcoin had no forecast to lean on. It jumped to about $87,100 after the jobs data, then slid to near $84,860 by afternoon as the 10-year turned higher. Coinbase (COIN) rose as much as 5.8%, then traded down 3.6%, and Strategy (MSTR) gave back a 6% gain. All of it happened on the Nasdaq's record day. Leverage may have mattered too. |
Outlier Signal The same rate shock is hitting every asset, and only fast-growing profits can absorb it. Stocks with record guidance trade a lower multiple for higher earnings, while bitcoin and the average stock take it in price. The usual read says stocks are ignoring bonds. They aren't. Investors pay about a tenth less for each dollar of profit than in May, so the index has no rate cushion left. If this week's $119 billion of Treasury auctions push the 10-year past 5.3% while early reports keep beating, the split holds. If guidance slips, nothing else is holding up a market at 19 times. | 03 | AI Needs Revenue Its Customers Can't BudgetThe builders need trillions in new sales. The buyers can't say what they'll spend next month. |
| Anthropic Plans to Spend 100 Times Its RevenueAnthropic plans to spend $518 billion in coming years, more than 100 times its 2025 revenue, its IPO prospectus shows, Reuters reported. Bain says AI firms must find more than $4.2 trillion of new revenue within five years to fund the build-out. Sales today are far smaller. Cash flow no longer covers the gap. Alphabet (GOOGL), Amazon (AMZN) and Meta (META) have all seen annual free cash flow turn negative, sending them to debt markets. |
| Almost Nobody Knows What AI Will CostOnly 11% of 396 companies forecast their AI spending within 10% of the actual bill, a Mavvrik and Benchmarkit survey found. The meter is erratic. Academic and Microsoft researchers ran models through more than 6,800 tasks, and cheaper models cost more in 32% of cases. In one test, Google's lighter Gemini model took 952 steps, ran up $14 and failed, while the pricier one finished for $1. Even the same model costs different amounts on the same prompt. Price per token tells a buyer almost nothing. |
Outlier Signal The build-out is priced on AI revenue rising steadily for years, but buyers see a meter they can't predict. For now that flatters vendors, since runaway usage gets billed. The obvious risk is that companies won't adopt AI. Adoption isn't the problem. Budgeting is. Finance teams answer surprise bills with caps and cheaper-model rules, turning open-ended usage into smaller, fixed spend just as the industry needs $4.2 trillion more. Labs and debt-funded hyperscalers carry that risk. If late-October cloud results show AI revenue keeping pace with capital spending, the meter is converting. If executives start citing usage caps, it is being budgeted down.  All three signals point the same way. The cost of carrying oil, money and AI is moving to whoever has the smallest cushion... truckers, stocks without earnings, buyers without a forecast. Strong volumes hid the shift. This week's Treasury auctions, Europe's storage data and early third-quarter guidance will show whether those cushions hold. |
|


